your career as an investor: what’s working against you?
Most people think about their career in terms of how many years they’ll spend working. Maybe you’ll work for 30 years. Maybe 40. You’ll get raises, change jobs, and eventually reach the point where you’re ready to retire.
But there’s another career happening alongside your regular one: Your career as an investor.
For 30 or 40 years, your money is supposed to be working toward the same goal: helping you build enough wealth to support the life you want in retirement. That’s a long time. And over that many years, plenty of things can quietly work against you.
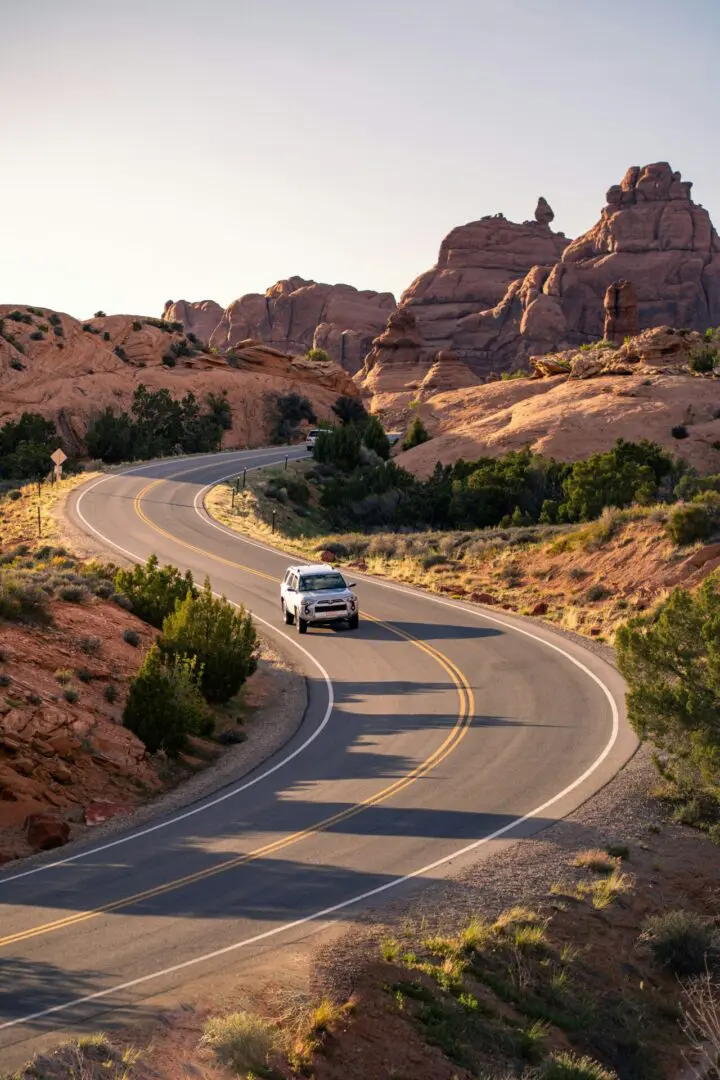
Think of your investing career like a long road trip
Imagine taking a road trip that lasts 30 to 40 years. You know where you’re going, and you’ve planned your route. But along the way, you run into unnecessary detours, expensive tolls, and unexpected expenses. One wrong turn might not seem like a big deal. Neither does spending a few extra dollars here and there. However, when those things happen repeatedly, they can add up.
Investing over time works the same way. Excessive fees, tax inefficiencies, inflation, and holding too much cash can all create drag on your portfolio. Individually, these factors might seem small. Over several decades, though, they can make a meaningful difference in how much wealth you ultimately accumulate.
Your Investing Career Has Different Stages
Just like your regular career, your investing career changes as you get older. Your strategy at 25 probably shouldn’t look exactly like your strategy at 60.
Early career: Focus on growth
When retirement is decades away, you generally have more time to recover from market downturns. Your investment strategy may focus more heavily on long-term growth. Consistent contributions and allowing compounding to work can help build the foundation of your retirement savings.
Mid-career: Build on what you’ve accumulated
As your income grows and your financial responsibilities change, your investment strategy may need to change, too. You might have multiple retirement accounts, larger balances, and more complicated financial decisions.
Now it’s important to make sure everything works together. Are your investments aligned with your goals? Are you paying unnecessary fees? From a tax perspective, are your accounts structured efficiently?
Approaching retirement: Protect what you’ve worked for
As retirement gets closer, your priorities may shift again. You still need your money to grow, but you also need to consider income, withdrawals, and the risk of selling investments during an unfavorable market.
Your portfolio shouldn’t be on autopilot for 30 or 40 years. It should be evaluated as your life and goals change.
What’s Dragging Down Your Progress?
Think back to that road trip. You can have a great destination and a reasonable route, but unnecessary expenses and detours can still get in the way. Investing works the same way. Here are a few things that can quietly work against your progress:
- Excessive fees: Money spent on unnecessary investment costs is money that can’t remain invested and potentially grow.
- Tax inefficiency: Holding certain investments in the wrong types of accounts or overlooking tax consequences can create unnecessary tax bills.
- Inflation: Even when your account balance increases, inflation can reduce what that money will actually buy in the future.
- Too much cash: Holding more money on the sidelines than your situation requires can limit its opportunity for long-term growth.
- An outdated strategy: A portfolio that made sense 15 years ago may not make sense today.
Pay particular attention to expensive investment products. An expensive product isn’t automatically a bad investment, but you should understand what you’re paying for and whether the added cost provides meaningful value.
You could spend decades contributing to your IRA and investing consistently. However, if unnecessary costs continually eat away at your returns, you may not end up with what you expected. It’s not just about how much you put in. It’s also about how much you get to keep.
Make Your Investing Career Count
Think about how much your regular career changes over 30 or 40 years. You learn new skills, take on different responsibilities, earn more money, and adjust your plans. Why should your investing career be any different?
Investing over time requires more than simply choosing a few investments and leaving them alone forever. It means periodically reviewing your fees, taxes, investment choices, and overall strategy to make sure they still fit. Sometimes, it takes another set of eyes to spot things you might have overlooked. You may have old retirement accounts, expensive products, unnecessary fees, or investments that no longer fit your timeline.
Everyone only gets one shot at their investing career. You can’t go back 15 years and eliminate fees you didn’t need to pay or recover years of potential growth you missed. However, you can take a closer look at where you are today and make adjustments for the years ahead.
At J Benjamin Financial, we can help evaluate your portfolio, identify potential sources of wealth drag, and determine whether your current strategy still makes sense. You’ve spent decades building your career. Make sure your money has been working just as hard.