Wealth Drag: The Money That Never Shows Up
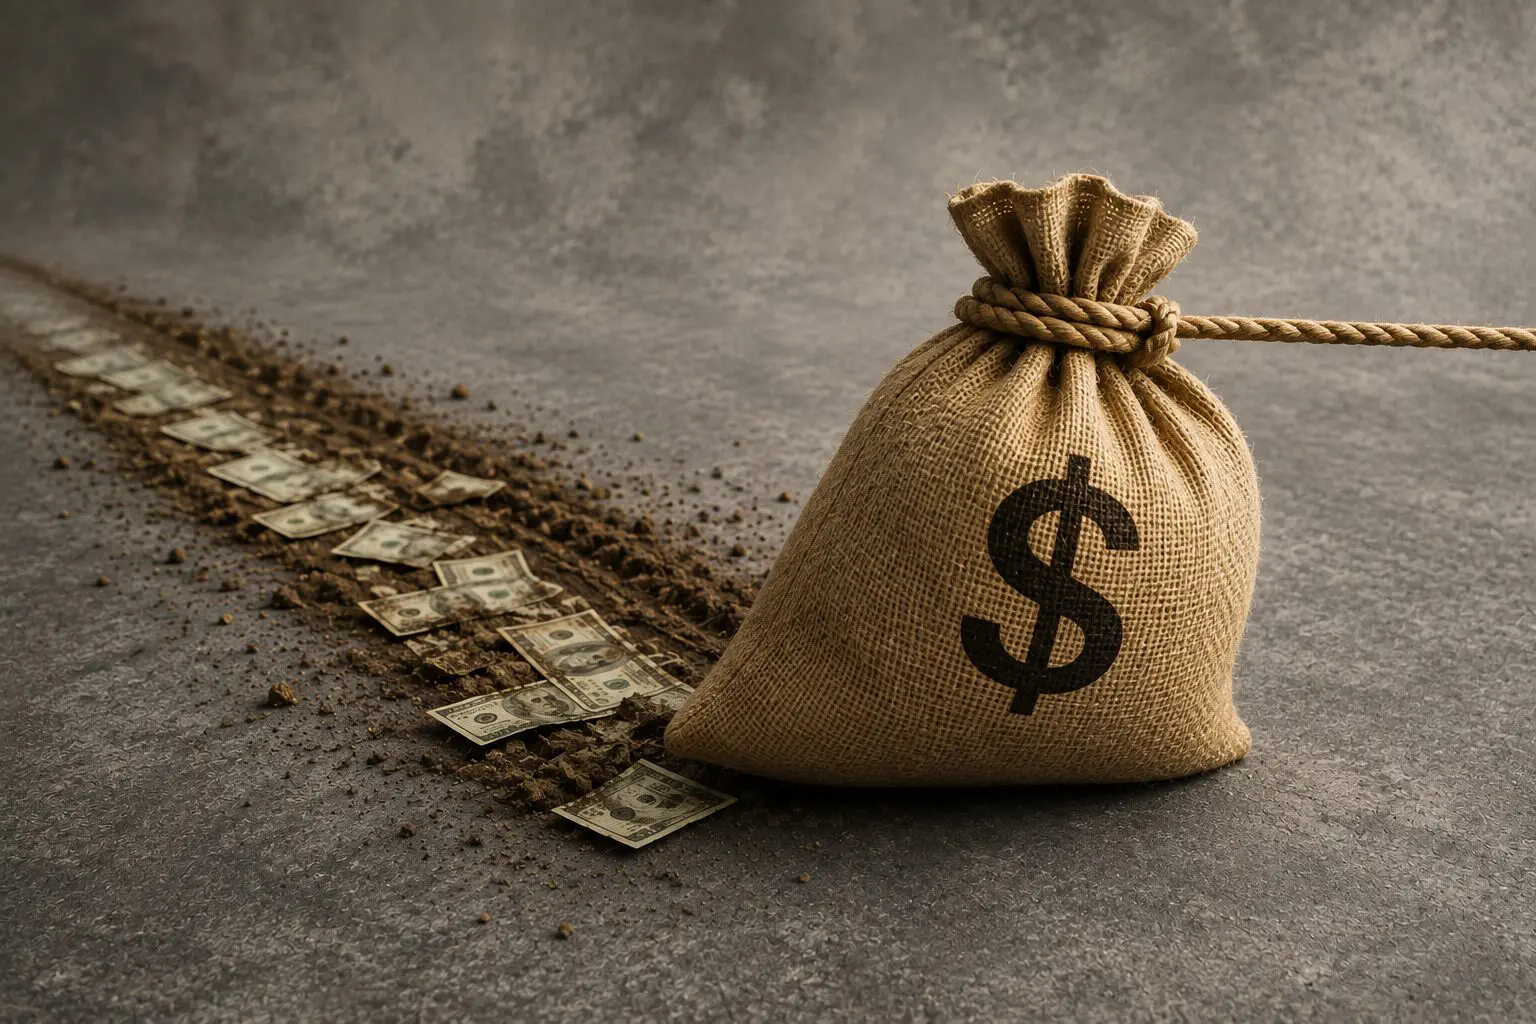
When you think about investment losses, you probably think about a market dropping 10%, 20%, or even more. But there’s another kind of loss that doesn’t show up quite as clearly. It’s called wealth drag.
Wealth drag is the slow, often overlooked erosion of your money caused by things like investment fees, taxes, and inflation. You may not see a big number disappear from your account all at once. Instead, these forces quietly reduce the amount of wealth you could have accumulated over time. And that can add up. Here are the common sources of wealth drag worth understanding:
1. Excessive Management Fees
Investment management fees are one of the more obvious forms of wealth drag, but it’s not always as simple as looking at a single fee and deciding whether it’s “high” or “low.” Different firms structure their fees in different ways. Some charge a flat rate, meaning the same percentage applies regardless of how much you have invested. Others use a sliding scale, where the percentage gradually decreases as your portfolio grows.
There are also situations where investors may be paying unnecessary or excessive management feeds without realizing it. Multiple layers of fees, expensive investment products, or services they aren’t actually using can quietly eat away at their returns.
The important thing isn’t simply finding the lowest fee possible. It’s understanding what you’re paying, what you’re receiving in return, and how those costs affect your wealth over time. Because just like taxes and inflation, money spent on unnecessary fees is money that can’t remain invested and potentially grow for your future.
2. Tax Inefficiency
Taxes are another potential source of wealth drag. It’s not just about how much you pay in taxes, but about where your investments are held. Certain investments may be more tax-efficient in a taxable account, while others may be better suited for tax-deferred or tax-free accounts.
For example, actively managed mutual funds can sometimes generate capital gains distributions when the fund manager buys and sells investments – even if you didn’t personally sell anything. You could end up receiving a taxable distribution simply because of activity happening inside the fund.
That doesn’t necessarily mean actively managed funds are bad. It means that understanding the tax consequences of what you own – and where you own it – can be important.
3. Inflation Erosion
Then there’s the wealth drag you can’t see on your investment statement: inflation. Your account might show that your money increased over time, but that doesn’t necessarily mean your purchasing power increased by the same amount.
If something costs $100 today and inflation averages 3% per year, that same item would cost roughly $181 in 20 years. So while your account balance may be growing, the purchasing power of each dollar can be shrinking. That’s why investing isn’t simply about accumulating more dollars. It’s about making sure those dollars continue to have the ability to support the life you want.
The Money You Don’t Know You’re Missing
What’s interesting about wealth drag is that it often represents the money you never see. You don’t receive a bill for the investment growth you didn’t earn. You don’t get a statement showing the purchasing power inflation took away. And you may not notice the long-term impact of paying slightly higher fees or holding tax-inefficient investments. That’s what makes wealth drag worth paying attention to.
It’s not about trying to eliminate every fee, avoid every tax, or outsmart inflation. Those things are part of investing. It’s about understanding how they affect your financial picture and making intentional decisions where you can. A little bit of drag may not seem like much today, but after 20-30 years, it can become a very different number.
If you’re concerned about your portfolio, give us a call. We’d be happy to take a look and help identify areas where wealth drag may be affecting your investments.